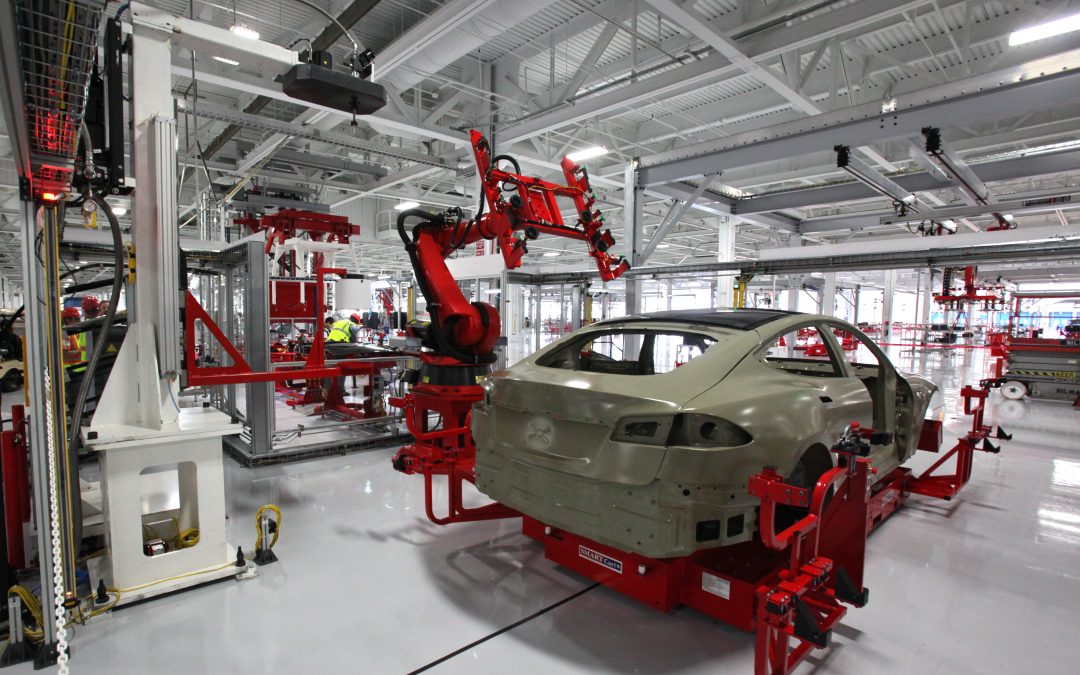
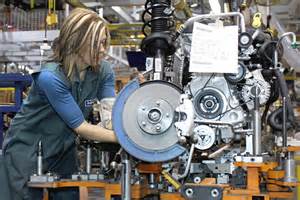
Manufacturing could offer a career with upward potential for STEM students at low-profile colleges.
The college graduates of 2015 were the most indebted ever — until the next round of grads wave their diplomas in the spring. But is sinking deep into debt really the ticket to a great career? If you have the means (and brains) to invest in an Ivy League degree, all stats seem to indicate you get ample payback for the $200,000-plus expense.
But among those high school grads who may not qualify for generous financial aid packages and at the same time cannot afford — or even want — an Ivy League degree, there are still lucrative options, especially if they study science, technology, engineering, and math (STEM).
The skills gap in U.S. manufacturing, for example, is well known. While as many as 60% to 70% of executives say their current employees lack sufficient skills in technology, computer, and math, the problem is exacerbated by the lack of qualified job prospects — an expected 2 million manufacturing jobs will go unfilled due to the talent gap during the next decade, according to a Deloitte study.
As I’ve said before, herein lies opportunity. There is no reason seeking a career in manufacturing should break the bank if students weigh their choices wisely. Picking a low-profile school may “pay off big both in terms of getting a good job and salary,”according to John Walsik, a Forbes contributor and author of The Debt-Free Degree.
The opportunity is best illustrated by Business Insider’srecent list of underrated colleges in America in which the US News and World Report’s rankings of the best universities was compared with PayScale’s 2015-2016 College Salary Report. Rather than pursuing degrees from the highest rated schools, high school grads should also consider schools that, although ranked relatively low on the US News list, yield high mid-career salaries.
Interestingly, Missouri University of Science and Technology, New Jersey Institute of Technology, and University of Massachusetts at Lowell, known for their science and engineering programs, all ranked in the top 5 (Pace University in New York City topped the list), with mid-career median salaries ranging from $94,700 to $102,000. Within six months of graduation, for example, 80% of New Jersey Institute of Technology graduates were either employed — top employers include IBM and ExxonMobil — or enrolled in graduate programs.
A college degree from a prestigious school means little unless your earnings quickly make it worthwhile. If only manufacturing could shake its lackluster reputation, a growing number of students may discover it holds the key to a career with a lot of upward potential — without necessarily going into big debt.
What is your take on the cost of college versus the payoff?
A version of this post previously appeared at EBN Online.
As companies “tiptoe” back to the United States from overseas, the “Made in USA” label should grow more common. However, ambiguous rules are costing some manufacturers hundreds of thousands of dollars in penalties and legal fees. So what’s the problem? The coveted “Made in USA” does not always mean the same thing to companies as to the Federal Trade Commission.
Although most cases stem from California, where every single component must be sourced domestically to earn the right to be advertised as American-made, the ambiguity of FTC’s rules is likely to bring more lawsuits nationwide. FTC rules state the “Made in USA” label can only go on goods that are “all or virtually all” made in the United States. But how should companies interpret “virtually?”
The latest to be slapped with a list of reprimands by the FTC is none other than Walmart, which recently was asked to not only remove “Made in USA” logos from all product listings, but also the country-of-origin information from all product specifications (unless required by law) and U.S.-origin claims that appear in product descriptions or titles. Walmart is also required to clear advertisement copy submitted by suppliers of any USA-origin claims.
A giant like Walmart can certainly handle adjustments to its Investing in America Jobs Program — redesigned logos will now disclose the percentage of U.S. content in the product — and transparency is obviously fundamentally important in sourcing and product advertisements. But the fact still remains: Companies can only guess what qualifies as U.S.-made. As reported by Supply Chain Digest, some have taken it upon themselves to include 70 percent of domestically made components before making any “Made in USA” claims.
The dysfunction is perhaps best illustrated by the case of Lifetime Products, whose basketball hoops ended up in the spotlight last fall when two consumer lawsuits claimed they were falsely labeled. Although the hoops are, to quote the Wall Street Journal, “made of parts that are almost entirely cut, shaped, painted and assembled” at the company’s sprawling Utah factory, some bolts and the net were imported from China. The costs were staggering, with the legal fees alone adding up to $535,000, and the plaintiff’s attorney’s receiving $485,000.
Sourcing every single component domestically is no easy feat, especially for companies that just returned production from overseas and want to capitalize on the move with the “Made in USA” label. After so many years of outsourcing, it will take time to rebuild the U.S. supplier base as well as upgrading aging manufacturing equipment to meet today’s demand for speed and agility.
Lasko Products Inc., a family-owned company based in West Chester, Pa., is one example of a producer that can no longer find domestic suppliers of small electric motors. The company’s electric fans are sold at Walmart, which has discovered the effort to buy more U.S.-made products has proved particularly difficult when it comes to electrical devices.
Let’s hope the FTC can at least clarify the rules.
What do you think is a reasonable definition of “Made in USA?”
The US manufacturing index is at its lowest level since 2009. This is sobering news for the industry and for the economy. Within the industry, it is clear that the road ahead is not flat, straight, or even smooth. For companies to not just survive, but to also succeed, action needs to be taken.
In August 2015 Bruce McDuffee, Principal at Knowledge Marketing for Industry, released the second edition of the Manufacturer’s Growth Manifesto. If you haven’t read this, you need to do so – today. In the Manifesto, McDuffee spells out how manufacturers can achieve growth rates of 10%, 20%, and even 30%.
The key to attaining a double digit growth rate is changing your marketing strategy and adapting to buyers’ new habits. Specifically:
Stop pitching products and start helping people.
Start educating your audience utilizing your particular experts and expertise for FREE.
Stop advertising product features and benefits of a product.
Start promoting your useful, helpful papers, webinars, seminars, videos, etc. (not product information) to foster meaningful engagement.
Admit to yourself and your team that your products are perceived as a commodity and it will take more than product revisions, releases and enhancements to gain the attention of your target audience.
McDuffee concedes that for those who have not previously embraced and engaged in this approach to marketing, “You may be thinking, WTF?”
It may seem counterintuitive, but the results are real. Your company will be able to achieve those double digit growth rates and realize these benefits:
Reciprocity, credibility and trust in the minds of the people in your target audience.
Top-of-Mind Awareness (T.O.M.A.) in the minds of your prospective customers so they remember your firm first when the day comes around and they need to buy.
Higher prices, more sales, more market share, and higher growth rates.
Success, however, depends on believing in this approach and incorporating it into your overall business strategy.
Research conducted by the Content Marketing Institute (CMI) found that while 82% of manufacturers use content marketing, only 26% say that their efforts are successful. A lack of buy-in/vision from higher ups is one of the key challenges identified by CMI. Another challenge that was reported was creating and executing a strategy; only 20% of respondents reported that they had a documented strategy. Notable though, is that 58% of the most effective companies reported that they have a documented strategy.
This approach is not relevant only to manufacturing. Companies across industries and verticals should take notice. Cerasis, a top North American third party logistics company offering logistics solutions with a strong focus on LTL freight management, shifted their marketing strategy and realized positive results. Within 25 months Cerasis realized a 14% increase in revenue. This increase was directly attributable to inbound marketing. In addition to this stream of revenue, the company’s sales team was able to generate revenue totaling $20 million during this period – more than double the previous two years combined.
We see that women in manufacturing and the supply chain haven’t been faring as well as their counterparts in other sectors. The number of women working in manufacturing is the lowest it has been since 1971. In the supply chain, men hold between 70-80% of the jobs, and we see even more disparity at the higher levels — only 5% of women hold Fortune 500 supply chain top-level positions.
Beth Ford, executive vice president and chief supply chain and operations officer at Land O’Lakes, sees the positive in these numbers: “The representation of women in this area is not where it needs to be. At the same time, it could be viewed as tremendously exciting. The opportunities are there for women.”
Where opportunity lies
So what can be done to make changes that will benefit everyone, and the bottom line?
According to a Fronetics Strategic Advisors report on women in the supply chain, “it has been put forth that women are better suited for roles in supply chain management than men. Research conducted by SCM World found that the majority of men (63%) and women (75%) believe that the natural skill sets of women differ from those of men and that these differences are advantageous for supply chain management.”
There are several women (and men) working in the supply chain who are cheering for other women to join. According to an interview with Bravo Solution VP Mickey North Rizza, “While business has traditionally been a man’s world, more and more women are now in businesses. Most women by nature have been relationship-builders. They encourage, collaborate and innovate with others for the best outcome. It is only natural that these tendencies gravitate to the business world, and most importantly into supply chain.”
To see lean perfected – study the NASCAR pit. In a matter of seconds, the pit crew has changed tires, wiped down the windshield, filled up fuel, and given the driver a drink of water. Everything is in the right place at the right time. If only every distribution center would run that smoothly. What’s clear is that mastering inventory levels is central to the equation of eliminating waste, but inventory management is becoming a vexing problem for some organizations – compounded by multi-channel distribution, inadequate demand forecasting, and a lack of communication among appropriate parties.
Taking a closer look at the experiences of forerunner companies in their quests to master lean inventory management might just help your company avoid these top three snags.
Failure to Adapt Business Processes
In an effort to reduce merchandise sitting around on warehouse racks, some organizations take lean too far. The problem, in this case, is one of business process rather than software. While management sees the financial impact of cutting inventory, they tend to pay less attention to how it will affect operations. The heads of distribution quite frequently are not even invited to take part in the decision and find out only when fewer cases and pallets show up at receiving. Adapting business processes to involve the managers of procurement, finance, operations, and sales and marketing, is key to maximizing efficiency. In other words, open up the silo by building it in to your formal and informal processes.
Failure to Collaborate
Even with sophisticated demand forecasting models on hand, input from all parties is needed for an accurate assessment of inventory levels. And although demand forecasting can help an organization plan around high-level “what if” scenarios, it may not always be able to break it down on a granular level or take into account the increasing number of variables associated with multi-channel distribution. Collaboration is crucial.
Failure to Align Objectives
Sometimes the answer to the issue of inventory levels is counterintuitive. Even with lean as the driving force, the notion of optimization cannot be left out. In some instances, it makes sense to increase rather than minimize inventory if it will contribute to lowering your overall supply chain costs. Your business and inventory strategies need to align.
Despite the fact that in recent years the lean revolution has hit manufacturing, many organizations, especially retailers and wholesalers, have yet to apply lean principals. And among those who do dabble in lean, the focus tends to be on suppliers upstream rather than adding value to the end customer. As more and more businesses seek to tighten the management of their inventory in order to increase efficiencies, opportunities to address end customer value will emerge. Paul A. Myerson, professor in supply chain management, identifies store- and distribution operations as prime candidates since that’s where the most waste can be cut. He writes:
Distribution is all about optimizing the trade-offs between handling costs and warehousing costs, and maximizing the warehouse’s total cube—utilizing its full volume, while maintaining low materials handling costs and minimizing travel time.
Mastery of lean management principals will come for companies that are both successful in identifying new efficiency opportunities within their existing supply chain and navigating around the pitfalls of businesses that have instituted similar inventory management techniques.
Fronetics Strategic Advisors is a leading management consulting firm. Our firm works with companies to identify and execute strategies for growth and value creation.
Whether it is a wholesale food distributor seeking guidance on how to define and execute corporate strategy; a telematics firm needing high quality content on a consistent basis; a real estate firm looking for a marketing partner; or a supply chain firm in need of interim management, our clients rely on Fronetics to help them navigate through critical junctures, meet their toughest challenges, and take advantage of opportunities. We deliver high-impact results.
This article is part of a series of articles written by MBA students and graduates from the University of New Hampshire Peter T. Paul College of Business and Economics.
Melanie Payeur graduated from the University of New Hampshire in 2007 with a degree in Mechanical Engineering. She has since worked in various roles supporting manufacturing and packaging operations in the food and beverage industry.
Do you know where your byproducts go?
Manufacturing often produces some sort of physical byproduct. Examples range from plastic strapping on a pallet of corrugate boxes to carbon dioxide collected off a tank of fermenting beer. Byproducts are the unspoken of and often neglected “cousin” of manufacturing.
Byproducts of manufacturing can be compared to the stage crew at a Broadway show or on a Hollywood movie set. They serve an important purpose. Without the lights, cameras, and curtains, there is no show. Similarly, without plastic strapping, a pallet of corrugate would fall over during transport because it wasn’t properly secured.
The stars of the show are the finished goods on store shelves. Just like people don’t stick around to see the name of the on-set hair-stylist when the credits roll at a movie, consumers often don’t think about the byproducts associated with the packaged food they eat or other goods they purchase. It’s possible that they don’t even know these things exist.
However, consumers are becoming more conscious of supply chain issues. Many have an awareness what Fair Trade is in association with sourcing of products such as coffee and cocoa beans. They discuss agricultural sourcing and the ethical (or not) treatment of animals raised to be part of the food chain. Even the effects of emissions and chemical waste on the environment are among topics of which many consumers have some awareness.
Plastic old, Plastic new
What about the plastic strapping on that pallet of corrugate though? Where does it go? Who even knows it exists other than the operator that cuts it off the pallet in the factory? Could it become a plastic bottle someday? Or a swing set? Maybe it will become plastic strapping again?
While countless other types of byproducts exist, plastic is a particularly interesting example. Fluctuations in the price of petroleum are directly correlated to the price of brand new, non- recycled plastic pellets. It is completely possible, and often realistic, that it is less expensive to create brand new plastic strapping than it is to recycle old strapping.
Trailer Bags and Trash Bowls
Creative and novel uses of byproducts are happening today. One example is a Swiss company called Freitag who produces trendy messenger bags, wallets, and purses from old side panel tarps (popular on tractor trailers in Europe). At the end of their useful life on the road, these tarps are purchased by Freitag and sewn into functional accessories.
Another example specifically related to plastic are Garbage Bowls made famous by Food Network host, Rachael Ray. These bowls are made from recycled pieces of broken plates. There’s a byproduct in there somewhere!
While these are great examples of repurposing byproducts into something new, the truth is that Freitag was originally looking for a material that would create a durable and functional product. Lucky for them, reusing something that might have otherwise been thrown away is a great marketing story. They charge an average of $200 for a standard messenger bag. Is it realistic that the reverse situation can create profits? Can we find another use for production process byproducts which would create a trendy or otherwise highly desirable product?
Can we do better than throwing our byproducts away?
If it’s not a company’s core competency, it probably shouldn’t get into the business of designing handbags. However, as supply chain professionals, we should understand all of the byproducts of our manufacturing process; especially those related to materials that we source as inputs, like plastic strapping.
It is as important to look at the waste stream from our process as it is to examine how we source raw materials. Are we recycling our byproducts? Is there someone who is looking for our ‘trash’ as an input to their process? Do we have the opportunity to have a profitable side business as a coincidental supplier to someone else? At the very least, can we do better than throwing our byproducts away?
An example of success can be seen in the food manufacturing industry. Some companies donate or sell their byproducts to the Bakery Feeds Program. This organization creates animal feed out of food byproducts such as misshapen cupcakes and other edible process waste. It might be cost neutral to dispose of waste in this way, but that is better than otherwise paying for disposal.
I challenge you to examine the waste streams associated with your process. Identify where at least one of your byproducts could go. From here to there and there to here, your byproducts could end up anywhere.