As I have written about previously, the lack of gender diversity in the supply chain is not because women do not have the skillset and ability to succeed within the industry:
“Women are as capable as men when it comes to working within the supply chain industry. Indeed, it has been put forth that women are better suited for roles in supply chain management than men. Research conducted by SCM World found that the majority of men (63%) and women (75%) believe that the natural skillsets of women differ from those of men and that these differences are advantageous for supply chain management.”
As a woman working within the supply chain industry, I believe that it is important to discuss the lack of gender diversity and point to research highlighting why the industry needs to increase the number of women in all positions, including the C-suite. Additionally, it is just as important to highlight the incredible women who already are working within the industry.
This year I’m turning my focus to showcase the work that these trailblazing women are doing. I spoke with Kendrea Durr-Smith, director of global trade compliance at Arrow Electronics, Kelli Saunders, President of Morai Logistics, Hailey McKeefry, editor and chief at EBN, and Barbara Jorgensen, co-founder and managing editor, EPS News. I also invited Tania Seary, founder of Procurious, to share what is happening at her company, and Jennifer Cortez, director of marketing and communications at Transplace, to discuss the role of quality content within the industry. These interviews and stories will be shared over the next couple weeks.
As I share the work of even more women in the future, I look forward to continuing a dialogue that will hopefully facilitate welcoming more women to the industry.
There is no easy answer to the burning question why the onshoring movement refuses to truly take off.
The issue of onshoring is frequently painted in black and white. While the media often likens the return of companies to the United States from overseas to a stampede, skeptics may be too quick to downplay the positive impact of the recent movement in manufacturing.
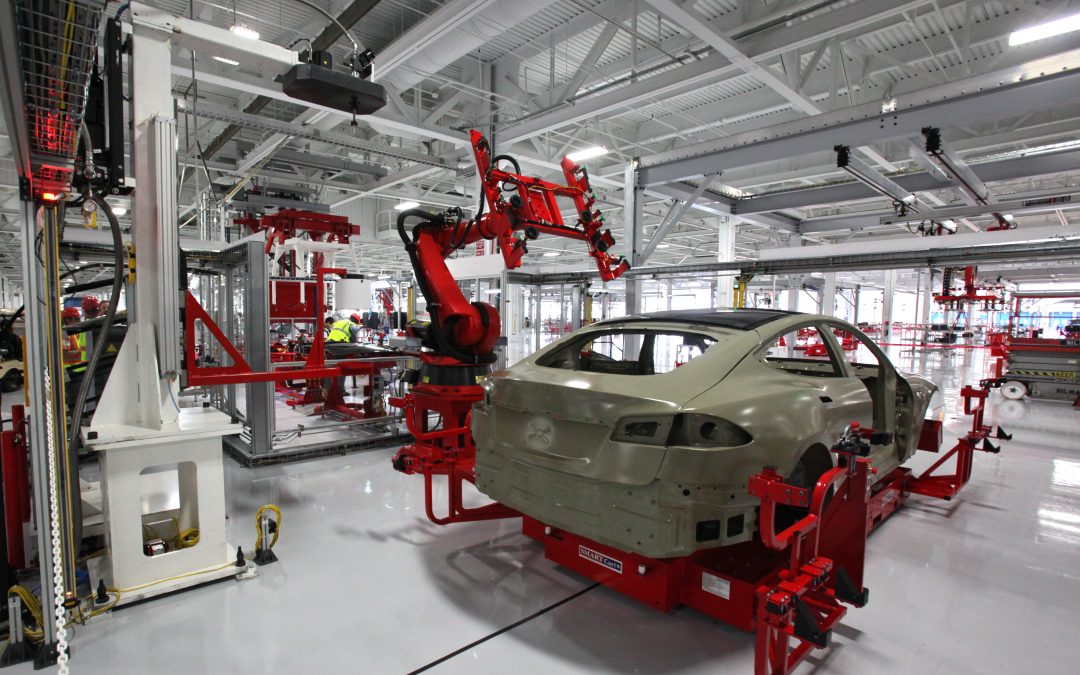
Nevertheless, those who were looking for a true Renaissance of American manufacturing have reason, at least so far, to be disappointed. Even among some high-profile companies — most notably Apple and GE — that announced their return with great fanfare, reality has set in. GE has battled high turnover rates at its re-opened Kentucky plants, as workers reportedly refused to perform certain tasks, while Apple has been stumped by the shortage of engineers.
Although the number of companies bringing production back home has risen significantly in recent years — from 64 in 2011 to 300 in 2014 — they are still outnumbered by those going in the opposite direction.
However, the issue is more complex than net gains or losses. According to new research by Morris Cohen, a Wharton School professor of operations and information management, and Hau L. Lee at Stanford University, “There is an unprecedented amount of restructuring going on.” In some cases, departments within the same company are onshoring and outsourcing at the same time, each weighing the perceived pros and cons differently.
In a Knowledge@Wharton interview, Cohen elaborated on the trend: “I’m going to go to China. I’m coming back from China. The same company simultaneously is making what seemed to be opposing decisions. And when you asked them why, they would give the same reasons. It’s because of labor costs. It’s because of market access. It’s because of this and that.”
In fact, they found there appears to be no dominant reason why companies make one decision or another in favor of onshoring or staying put.
And barriers seem to remain the same as when the onshoring movement began to gain momentum: The lack of skilled workers, coupled with an aging workforce, still rank high on the list of negatives. The rapid pace of offshoring in 1990s and early 2000s made younger generations lose faith in the viability of a manufacturing career.
Patrick Van den Bossche, the Americas lead partner at A.T.Kearney’s Strategic Operations Practice — which released its inaugural Reshoring Index last year — explained the problem on Manufacturing.net: “Think about it — if you have a kid in school, with everything that happened in the last few years, with manufacturing moving overseas as fast as it did, would you feel comfortable to tell your kid to develop a career in manufacturing? I don’t think so.”
At the same time, countries like China, Brazil, and Eastern Europe, previously known for their low-skilled labor, are quickly improving and investing in high-tech industries. With a greater pool of skilled workers abroad, a move back to the United States will seem less urgent. And with the arrival of robotics, the issue of labor costs will likely take on even less significance.
So the big question is, how should the United States stand up to the competition? What do you think?
A version of this article previously appeared on EBN Online.
Manufacturing could offer a career with upward potential for STEM students at low-profile colleges.
The college graduates of 2015 were the most indebted ever — until the next round of grads wave their diplomas in the spring. But is sinking deep into debt really the ticket to a great career? If you have the means (and brains) to invest in an Ivy League degree, all stats seem to indicate you get ample payback for the $200,000-plus expense.
But among those high school grads who may not qualify for generous financial aid packages and at the same time cannot afford — or even want — an Ivy League degree, there are still lucrative options, especially if they study science, technology, engineering, and math (STEM).
The skills gap in U.S. manufacturing, for example, is well known. While as many as 60% to 70% of executives say their current employees lack sufficient skills in technology, computer, and math, the problem is exacerbated by the lack of qualified job prospects — an expected 2 million manufacturing jobs will go unfilled due to the talent gap during the next decade, according to a Deloitte study.
As I’ve said before, herein lies opportunity. There is no reason seeking a career in manufacturing should break the bank if students weigh their choices wisely. Picking a low-profile school may “pay off big both in terms of getting a good job and salary,”according to John Walsik, a Forbes contributor and author of The Debt-Free Degree.
The opportunity is best illustrated by Business Insider’srecent list of underrated colleges in America in which the US News and World Report’s rankings of the best universities was compared with PayScale’s 2015-2016 College Salary Report. Rather than pursuing degrees from the highest rated schools, high school grads should also consider schools that, although ranked relatively low on the US News list, yield high mid-career salaries.
Interestingly, Missouri University of Science and Technology, New Jersey Institute of Technology, and University of Massachusetts at Lowell, known for their science and engineering programs, all ranked in the top 5 (Pace University in New York City topped the list), with mid-career median salaries ranging from $94,700 to $102,000. Within six months of graduation, for example, 80% of New Jersey Institute of Technology graduates were either employed — top employers include IBM and ExxonMobil — or enrolled in graduate programs.
A college degree from a prestigious school means little unless your earnings quickly make it worthwhile. If only manufacturing could shake its lackluster reputation, a growing number of students may discover it holds the key to a career with a lot of upward potential — without necessarily going into big debt.
What is your take on the cost of college versus the payoff?
A version of this post previously appeared at EBN Online.
As companies “tiptoe” back to the United States from overseas, the “Made in USA” label should grow more common. However, ambiguous rules are costing some manufacturers hundreds of thousands of dollars in penalties and legal fees. So what’s the problem? The coveted “Made in USA” does not always mean the same thing to companies as to the Federal Trade Commission.
Although most cases stem from California, where every single component must be sourced domestically to earn the right to be advertised as American-made, the ambiguity of FTC’s rules is likely to bring more lawsuits nationwide. FTC rules state the “Made in USA” label can only go on goods that are “all or virtually all” made in the United States. But how should companies interpret “virtually?”
The latest to be slapped with a list of reprimands by the FTC is none other than Walmart, which recently was asked to not only remove “Made in USA” logos from all product listings, but also the country-of-origin information from all product specifications (unless required by law) and U.S.-origin claims that appear in product descriptions or titles. Walmart is also required to clear advertisement copy submitted by suppliers of any USA-origin claims.
A giant like Walmart can certainly handle adjustments to its Investing in America Jobs Program — redesigned logos will now disclose the percentage of U.S. content in the product — and transparency is obviously fundamentally important in sourcing and product advertisements. But the fact still remains: Companies can only guess what qualifies as U.S.-made. As reported by Supply Chain Digest, some have taken it upon themselves to include 70 percent of domestically made components before making any “Made in USA” claims.
The dysfunction is perhaps best illustrated by the case of Lifetime Products, whose basketball hoops ended up in the spotlight last fall when two consumer lawsuits claimed they were falsely labeled. Although the hoops are, to quote the Wall Street Journal, “made of parts that are almost entirely cut, shaped, painted and assembled” at the company’s sprawling Utah factory, some bolts and the net were imported from China. The costs were staggering, with the legal fees alone adding up to $535,000, and the plaintiff’s attorney’s receiving $485,000.
Sourcing every single component domestically is no easy feat, especially for companies that just returned production from overseas and want to capitalize on the move with the “Made in USA” label. After so many years of outsourcing, it will take time to rebuild the U.S. supplier base as well as upgrading aging manufacturing equipment to meet today’s demand for speed and agility.
Lasko Products Inc., a family-owned company based in West Chester, Pa., is one example of a producer that can no longer find domestic suppliers of small electric motors. The company’s electric fans are sold at Walmart, which has discovered the effort to buy more U.S.-made products has proved particularly difficult when it comes to electrical devices.
Let’s hope the FTC can at least clarify the rules.
What do you think is a reasonable definition of “Made in USA?”
The health care supply chain could cut billions of dollars in cost by adopting practices well established in other industries.
Take the case of a typical Asian laptop manufacturer, for example. As a result of a top-notch supply chain, a European customer can place an order and receive a pallet of freshly assembled computers in just over a week. Ask a pharmaceutical manufacturer for a delivery, on the other hand, and the lead time stretches to 75 days.
The case is further illustrated by the difference in operational metrics between the health care supply chain and the supply chain for fast-moving consumer goods (FMCG). Whether you look at days in inventory, obsolescence, or manufacturing lead time, the FMCG is invariably so efficient that the health care supply chain looks sluggish in comparison.
But such a significant performance gap also means even minor efficiency gains could have a big impact, according to a McKinsey report. An industry that spends in the excess of $340 billion annually on pharmaceuticals and medical devices would benefit from examining every part of its supply chain to not only speed up lead time and boost ROI, but also provide safer and more affordable products to end customers around the world, the consulting firm argues.
The shortcomings so far stem from an inability to tackle challenges that today add substantial cost to the health care supply chain. Big-ticket challenges include:
Increased regulatory scrutiny
Expanding product portfolios
Drug recalls
Drug shortages
Counterfeiting
Supply-chain security breaches
Medication errors in the developed world
Although transforming a supply chain is an incredibly complex undertaking, McKinsey notes:
“…if the sector adopted straightforward advances well established in other industries, we estimate that total costs (from the supply chain and external areas, such as patient care) could fall by $130 billion.”
Industry research does indeed show every member of the value chain – from pharmaceuticals and medical suppliers to pharmacies and hospitals – that embraces opportunities to optimize the health care supply chain reaps the rewards in increased profitability. In most cases, the impact on profits ranged from 10 to 20 percent.
So which area of the supply chain offers the greatest opportunity for improvement?
Senior supply chain executives in the pharmaceutical and medical device industries overwhelmingly place improved collaboration at the top of the list. To overcome cultural barriers and make transactional relationships more productive, McKinsey suggests the following approach:
“…six essential steps can make the difference between a productive collaboration and a frustrating one: companies must collaborate in areas where they have a solid footing; agree on sophisticated benefit-sharing models; select partners for the potential value of the collaboration, as well as their capabilities and willingness to act as a team; dedicate resources to the collaboration and involve senior leadership in it; jointly manage performance and measure impact; and start out with a long-term perspective.”
Collaboration is still only a small piece in the supply chain puzzle that also includes better market, product, and customer segmentation; greater agility; improved benchmarking and measurements; and the establishment of global standards for data exchange. To put it all together, it is imperative for the health care supply chain to follow the lead of high performing industries.
The US manufacturing index is at its lowest level since 2009. This is sobering news for the industry and for the economy. Within the industry, it is clear that the road ahead is not flat, straight, or even smooth. For companies to not just survive, but to also succeed, action needs to be taken.
In August 2015 Bruce McDuffee, Principal at Knowledge Marketing for Industry, released the second edition of the Manufacturer’s Growth Manifesto. If you haven’t read this, you need to do so – today. In the Manifesto, McDuffee spells out how manufacturers can achieve growth rates of 10%, 20%, and even 30%.
The key to attaining a double digit growth rate is changing your marketing strategy and adapting to buyers’ new habits. Specifically:
Stop pitching products and start helping people.
Start educating your audience utilizing your particular experts and expertise for FREE.
Stop advertising product features and benefits of a product.
Start promoting your useful, helpful papers, webinars, seminars, videos, etc. (not product information) to foster meaningful engagement.
Admit to yourself and your team that your products are perceived as a commodity and it will take more than product revisions, releases and enhancements to gain the attention of your target audience.
McDuffee concedes that for those who have not previously embraced and engaged in this approach to marketing, “You may be thinking, WTF?”
It may seem counterintuitive, but the results are real. Your company will be able to achieve those double digit growth rates and realize these benefits:
Reciprocity, credibility and trust in the minds of the people in your target audience.
Top-of-Mind Awareness (T.O.M.A.) in the minds of your prospective customers so they remember your firm first when the day comes around and they need to buy.
Higher prices, more sales, more market share, and higher growth rates.
Success, however, depends on believing in this approach and incorporating it into your overall business strategy.
Research conducted by the Content Marketing Institute (CMI) found that while 82% of manufacturers use content marketing, only 26% say that their efforts are successful. A lack of buy-in/vision from higher ups is one of the key challenges identified by CMI. Another challenge that was reported was creating and executing a strategy; only 20% of respondents reported that they had a documented strategy. Notable though, is that 58% of the most effective companies reported that they have a documented strategy.
This approach is not relevant only to manufacturing. Companies across industries and verticals should take notice. Cerasis, a top North American third party logistics company offering logistics solutions with a strong focus on LTL freight management, shifted their marketing strategy and realized positive results. Within 25 months Cerasis realized a 14% increase in revenue. This increase was directly attributable to inbound marketing. In addition to this stream of revenue, the company’s sales team was able to generate revenue totaling $20 million during this period – more than double the previous two years combined.